
What is the metal scrap reverse charge?
Normally the seller charges 5% VAT and pays it to the FTA. Under the reverse charge, the seller charges no VAT.
The buyer calculates the 5% itself, reports it in its own VAT return and, if entitled, recovers it in the same return.
The rule comes from Cabinet Decision No. 153 of 2025 and covers supplies made on or after 14 January 2026. In October 2026 the Federal Tax Authority (FTA) explained how to apply it in VAT Public Clarification VATP047.
| At a glance | Position under VATP047 |
|---|---|
| Legal basis | Cabinet Decision No. 153 of 2025, issued under Article 48(8) of the VAT Law |
| Applies to | Qualifying metal scrap supplied on or after 14 January 2026 |
| Who must be VAT-registered | Both the supplier and the buyer |
| Buyer's purpose | Resale, or use in processing |
| Who accounts for VAT | The buyer, if every condition is met |
| Paperwork deadline | Before the date of supply |
| Buyer's VAT return | Box 3, with recoverable tax in Box 10 |
| Exports | Outside the mechanism |
Reverse charge is not an exemption. VAT is still due. Only the business that accounts for it changes.
How the numbers work on AED 100,000
Normal VAT
The supplier collects AED 5,000 and reports it in its return.
Reverse charge
If fully entitled, the buyer reports AED 5,000 as output VAT and recovers AED 5,000 as input VAT.
The net VAT here is zero. The gain is cash flow: the buyer never pays AED 5,000 to the supplier upfront. That holds only if the sale qualifies and the buyer can recover in full.
Which metal scrap is covered?
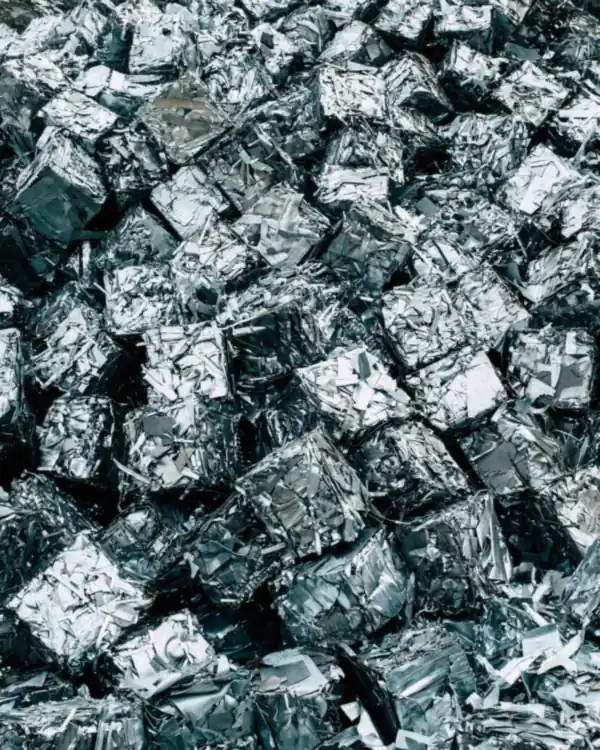
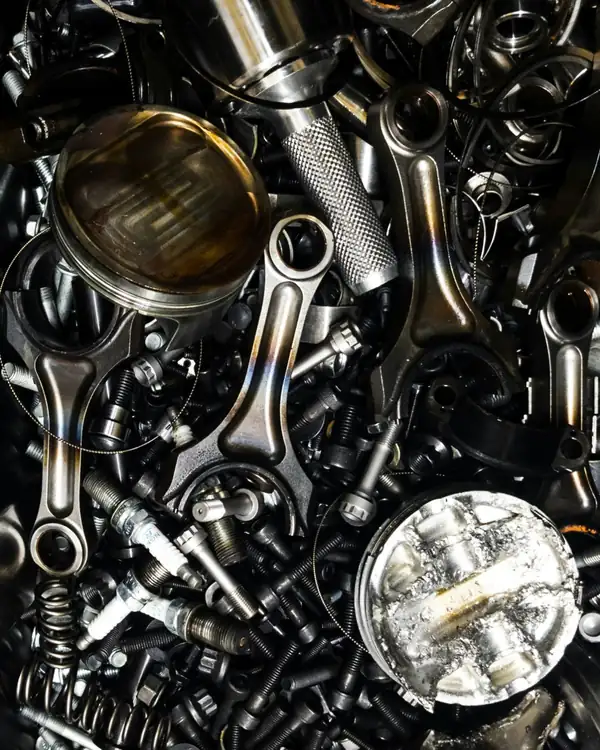
Metal scrap means ferrous or non-ferrous metal waste with commercial value that can be used after processing. The legal definition decides, whatever the product is called.
Not covered: these stay under normal VAT
- Plastic
- Paper and cardboard
- Glass
- Rubber
- Textiles
- Organic waste
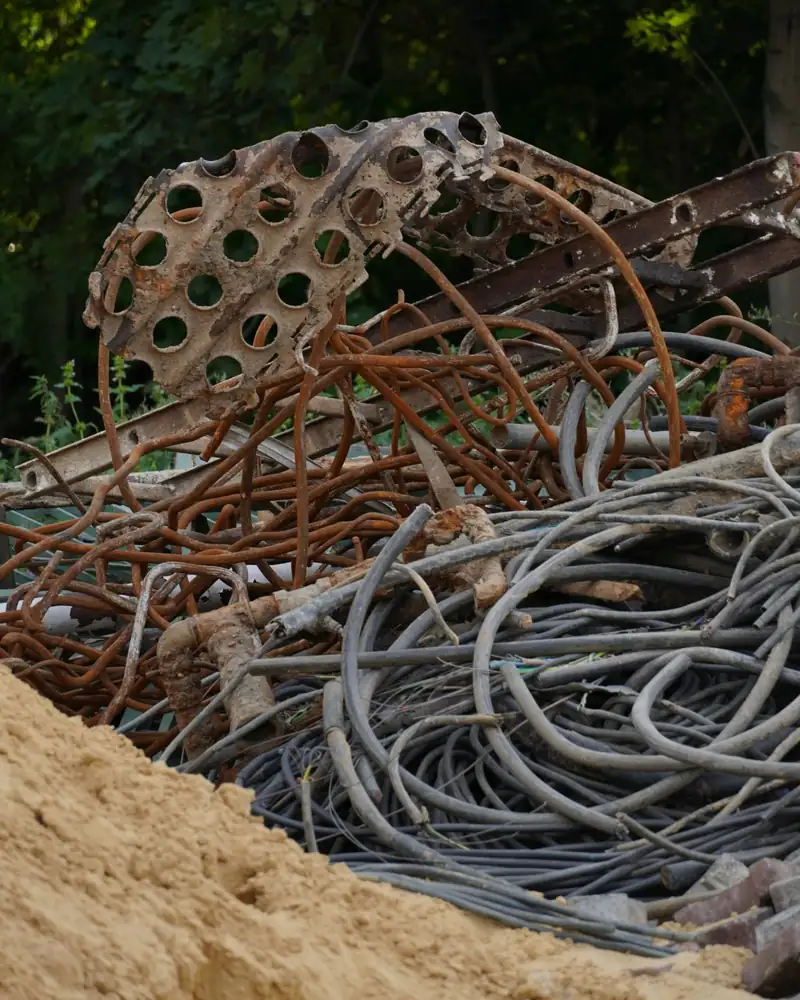
Mixed loads need line-by-line treatment
A recycler trading metal and non-metal scrap cannot run one VAT treatment across every purchase and sale. Classify each line. Qualifying metal follows the reverse charge; everything else follows the normal rules.
Used lead-acid batteries can qualify where lead is most of the product and the main material recovered. Small amounts of plastic or electrolyte do not change that.
When does the reverse charge apply?
All four conditions must be met: the goods are qualifying metal scrap, both businesses are VAT-registered, the buyer intends to resell or process the scrap, and the paperwork is done before the supply.
| Buyer's purpose | Reverse charge? |
|---|---|
| Resale: bought as trading stock and sold on, wholesale or retail | Yes, if the other conditions are met |
| Processing: turned into material for new products, by repair, recycling or another method | Yes, if the other conditions are met |
| Own use: for example repairing racks, fences or supports at your premises | No, normal VAT rules apply |
What must the buyer do?
Before the date of each supply, give the supplier two written declarations. The FTA allows both in one document.
Declare the intended use
Confirm the metal scrap is bought for resale or for use in processing.
Declare your VAT registration
Confirm you are registered for UAE VAT, with details such as your Tax Registration Number (TRN).
Sample declaration, adapt before use
Metal Scrap Reverse Charge Declaration
We, [Buyer Legal Name], holding UAE VAT TRN [TRN], confirm that we are registered for UAE Value Added Tax.
We further confirm that the metal scrap described in [Purchase Order / Transaction Reference] is being acquired with the intention of resale or processing within the meaning of Cabinet Decision No. 153 of 2025.
This declaration is provided to the supplier before the date of supply for the purposes of applying the relevant reverse charge provisions.
Link each declaration to its purchase order, invoice and delivery record. An unsigned form, a statement collected after delivery, or a TRN in a customer file is unlikely to be enough.
What must the supplier do?
Three checks, all before the date of supply.
Receive and keep the declarations
Hold the buyer's written confirmation of registration and intended use.
Verify the TRN with the FTA
Use the TRN verification tool on the FTA website. A number quoted on a purchase order is unverified until you check it.
Say so on the tax invoice
State clearly that the reverse charge applies, alongside every other detail a valid tax invoice needs.
Sample invoice wording
Reverse Charge Mechanism applies to this supply of metal scrap under Cabinet Decision No. 153 of 2025. The recipient is responsible for accounting for the applicable VAT.
Removing the 5% line from an invoice is never enough on its own. Keep the declarations and verification records with the invoice.
What if the declaration is missing?
The reverse charge fails. The supplier must charge VAT at the standard 5% and report the sale in Box 1 of its return.
The buyer also loses the right to recover that VAT. Article 2(4) of Cabinet Decision No. 153 of 2025 stops it treating the scrap as used for the purposes in Article 54(1)(a) and (b) of the VAT Law.
Collect the declarations before supply, every time.
How do you report it in the VAT return?
| Who and when | VAT return treatment |
|---|---|
| Supplier, conditions met | Leaves the supply and its VAT out of its return |
| Buyer, reverse charge | Declares the supply in Box 3 |
| Buyer, recoverable tax | Recovers it in Box 10, never Box 9 |
| Supplier, declarations missing | Reports a standard-rated supply in Box 1 |
The sale still goes in the supplier's books for bookkeeping, revenue and financial reporting. Only the VAT treatment changes. For the buyer, full recovery follows legal entitlement, never habit.
Check your accounting software
One domestic VAT code for everything is where errors start. Your system, whether Zoho Books or another platform, should separate:
- Standard-rated domestic sales and purchases
- Qualifying reverse charge metal scrap
- Exports qualifying for zero-rating
- Other supplies with their own VAT treatment
Then check tax codes, invoice templates and VAT return mapping against the FTA guidance. Our UAE bookkeeping and accounting service keeps these classifications right.
Do metal scrap exports count?
No. Direct and indirect exports sit outside Cabinet Decision No. 153 of 2025. Where the zero-rating conditions are met, the supplier reports the export as a zero-rated supply under the normal rules.
Planning to ship goods abroad does not, by itself, meet those conditions. Check each export against the rules and the evidence they require.
Four quick examples
| Situation | Likely VAT treatment |
|---|---|
| A scrap dealer buys steel scrap to resell, gives both declarations before supply, and the supplier verifies the TRN and invoices correctly | Reverse charge |
| A manufacturer buys aluminium scrap to recycle into material for new products, with declarations and verification complete | Reverse charge |
| A warehouse company buys scrap metal to repair its own storage racks | Normal VAT: neither resale nor processing |
| A dealer buys copper scrap to resell but gives no declarations before supply | Standard rate, and the buyer cannot recover the input VAT |
What should you check now?
VATP047 arrived in October 2026, but the rule has applied since 14 January 2026. Review from that date.
Classification
Which lines are qualifying metal scrap, with non-metal scrap kept out.
Eligibility
Both parties VAT-registered, and the buyer's stated use meets the conditions.
Declarations
Received before each supply and linked to the right transaction.
TRN checks
The buyer's registration verified through the FTA tool.
Invoices
Reverse charge wording on every qualifying invoice.
VAT returns
Buyer side in Box 3, recovery in Box 10, never Box 9.
Past gaps
Transactions with a doubtful treatment or missing documents.
Assess any correction against the tax procedures and the facts before amending a return or considering a voluntary disclosure. Do not assume a declaration written after the event cures a missed pre-supply requirement.
Frequently asked questions
When did the metal scrap reverse charge start in the UAE?
Is every metal scrap sale in the UAE subject to reverse charge?
Is a customer's TRN enough to apply reverse charge?
Can the buyer recover VAT if it did not provide the declarations?
Which VAT return boxes does the buyer use?
Does the rule apply to free zone companies?
Sources: FTA VAT Public Clarification VATP047 (October 2 (opens in a new tab), the Ministry of Finance announcement (opens in a new tab), and Cabinet Decision No. 153 of 2025 on the UAE Legislation Portal (opens in a new tab). General information, not tax advice for a specific transaction.